SpaceX's IPO is two-times oversubscribed. Read that slowly.
A 2x book, $5.7B in liquidations, and a labour print at 2020 lows. The asymmetry is the story.
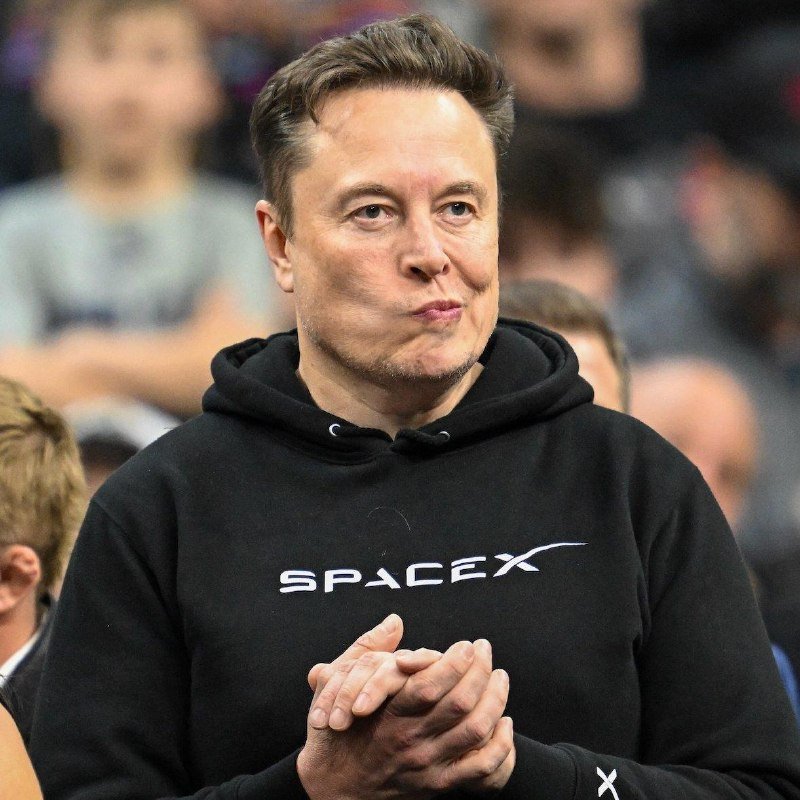
On 7 June 2026, an offering for shares of a private company with limited retail access was already oversubscribed by a factor of two. The news, circulated by Cointelegraph, landed in the same 24-hour window that the same wires reported $5.7 billion in leveraged long positions liquidated across crypto markets over a seven-day stretch, and that US small-business hiring was on track to print at its lowest level since May 2020. Three signals, one tape, two entirely different audiences reading it. The asymmetry between them is the story — and it has been a long time since the asymmetry was this loud.
The oversubscription of SpaceX's IPO is not a SpaceX story. It is a read on the cost of admission to the public market in 2026, and on who still gets a chair. The 2x book is being built by institutions that have already decided the price; a separate data point — Ethereum's staking queue, where 1,261 times more ETH is queued to stake than to unstake — tells you what the marginal dollar is doing when it cannot get into the deal it actually wants. The labour tape, meanwhile, is being set by an economy that is not in the room. The room, in this case, is an IPO subscription book built around a company that has never had to ask the public for money and is doing so now only because the cheque is too large to clear privately.
The 2x book, and what a book is for
A 2x oversubscribed book is a polite banker word for "we could double the size of this offering and still sell it." That is not a market signal of demand; it is a market signal of rationing. The book is a tool for allocating scarcity, and scarcity is being deliberately constructed — through the timing of the S&P 500 inclusion (per Reuters, SpaceX may have to wait until 2027), through the pricing of a private round before the listing, and through the long shadow of insiders and pre-IPO holders. The job of the book is to decide who gets the IPO pop and who pays for it six months later. The fact that the book is twice as deep as it needs to be tells you the bank has the latitude to be choosy. It always does. What is novel is the size of the choosers' war chest — and the gap between that war chest and the underlying small-business economy that will eventually be asked to underwrite the multiple.
The rekt tape as a tell
$5.7 billion in long liquidations in seven days is the kind of number that should cool an IPO. It has not. The reason is that the two audiences are barely overlapping. The leveraged longs being wiped out in crypto are typically retail-adjacent, prop-trading-adjacent, or funds running directional books on volatile underlyings — Ethereum perpetuals, altcoin perps, the high-beta end of the complex. The SpaceX book is being built by pensions, sovereign-wealth desks, multi-asset funds, and family offices that have already done their asset-allocation math. They are not selling ETH perps to buy SpaceX. They are issuing new cheques against a different liquidity pool entirely. The "everything is correlated" narrative is convenient for macro commentators and almost universally wrong in the precise moments when it matters most.
The labour tape nobody is pricing
The same morning the IPO rumour hardened into coverage, the small-business hiring print pointed to its weakest reading since May 2020. The small-cap, the small-employer, the main-street balance sheet — this is the part of the economy that has to actually hire the next waiter, the next electrician, the next junior accountant. That tape is not where the IPO book is built. It is, however, where the IPO book is eventually paid for, in taxes, in consumer demand, in political legitimacy. Morgan Stanley's projection of $3.4 trillion in SpaceX revenue by 2040 is, on the bank's own horizon, a 14-year forward bet. The main-street hiring print is a 14-week bet. Capital markets are explicitly pricing the longer one and explicitly ignoring the shorter one. That is a choice, and a structural one.
The staking queue as a proxy for what is being denied
The Ethereum staking queue shows 1,261 times more ETH waiting to be staked than waiting to be unstaked. That ratio is not bullish ETH per se; it is bullish permissioned access to yield. The marginal crypto dollar that cannot get into SpaceX at the IPO price, and cannot get into a venture secondary at a tolerable discount, is parking itself in a real-yield queue and waiting its turn. That is a tell. The IPO book is the explicit signal. The staking queue is the implicit one. They are both saying the same thing: the safe assets with a real return are rationed, and the people who get them are already known to the allocator.
The stakes here are not whether SpaceX is a good company. Morgan Stanley's $3.4 trillion revenue projection is an analyst number attached to a satellite-internet-plus-launch-services monopoly thesis; the actual print will depend on the next decade of launch cadence, defence procurement, and whether Starlink can keep its current pricing power in residential broadband. The stakes are whether the public market in 2026 is structurally capable of offering retail and working-class capital a seat at the table it keeps telling them to sit at. The S&P 500 inclusion delay to 2027 means passive flows will not price the stock for at least twelve more months. The IPO book is being filled by entities that have already decided. The liquidations, the small-business hiring print, and the staking queue are what the marginal dollar is doing when it has been told, in three different languages, that it is not on the list.
The 2x book is a triumph of salesmanship. The question is whether it is also the loudest possible signal of a market that has stopped pretending to be open.
How Monexus framed this: the wire cycle ran the 2x book and the $5.7B in liquidations as separate stories. They are the same story, told from two different balance sheets.
Wire provenance
This editorial synthesis draws on the following public wire/social posts:
- https://t.me/cointelegraph
- https://t.me/cointelegraph
- https://t.me/cointelegraph
- https://t.me/cointelegraph
- https://t.me/cointelegraph
- https://t.me/cointelegraph