The bond market won't take 'discreet' for an answer
Washington's messaging operation has stopped pretending the Treasury is a passive bystander. The yield curve isn't buying it.
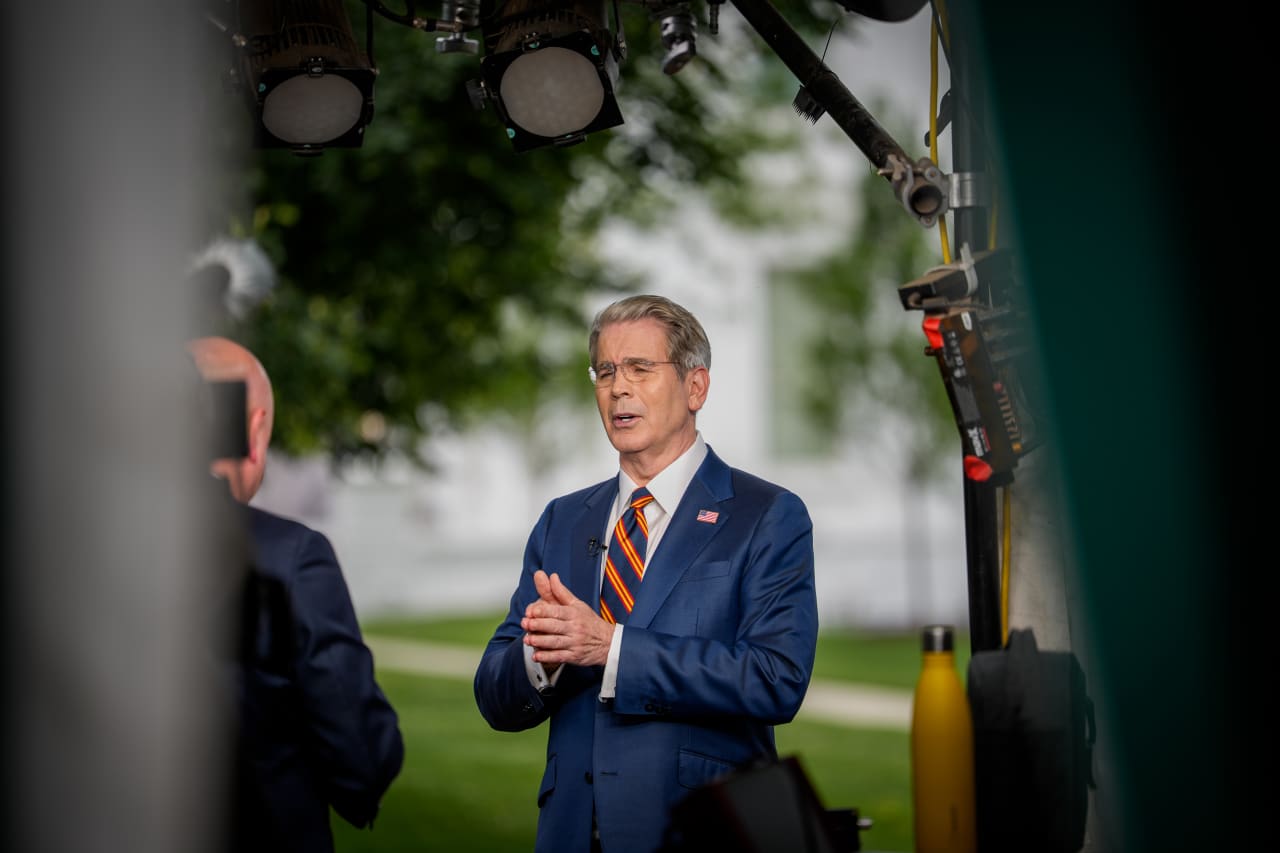
At 22:58 UTC on 21 August 2026, Scott Bessent was asked on camera whether the latest US jobs print meant the labour market was finally cracking. The Treasury Secretary replied that the data were "quite noisy." Forty minutes later, President Donald Trump told reporters that Bessent had acted independently in intervening to support the bond market, and that he, Trump, had not directed him to do so. By 00:31 UTC on 22 August, Vice President JD Vance had told a separate audience that Bessent and the President had, in fact, agreed on a "discreet" plan to push US growth above the debt curve. Three statements, one calendar day, three different stories about who is steering the world's most important securities market.
The bond market does not need to be told what to think. It reads. And on the evidence of the past 72 hours, what it has been reading is a US fiscal authority that cannot keep its own message straight while the curve steepens underneath it.
The alibi that wasn't
Start with Trump's denial. Reported across financial wires on 21 August, the President stated he had not directed Bessent to intervene in the bond market, framing the Treasury Secretary's actions as independent stewardship of market functioning. It is the textbook response of a Treasury that wants the appearance of a level playing field: the official line is that operations, if they happen, are technical, apolitical, and not steered from the Oval Office.
The problem is the surrounding cast. Vice President Vance, speaking the same evening, did not merely fail to back the denial. He confirmed the opposite: a coordinated, "discreet" plan between Bessent and Trump to engineer growth above the trajectory of federal debt. As reported by Unusual Whales on 22 August, Vance described the arrangement in language that left little daylight between the White House and the Treasury desk. Two officials, same administration, opposite versions of who decided what. The credibility damage is not that one of them is lying. It is that the administration felt compelled, on the same day, to give two stories.
"Quite noisy" is not a policy
Bessent's "noisy data" line deserves its own paragraph because it is the rhetorical move that is most likely to age badly. Asked whether the jobs report signalled a labour market cracking, the Secretary chose to discount the print rather than to contextualise it. Discounting is what officials do when the data point is inconvenient. Contextualising is what officials do when they want to keep their credibility for the next print.
This is a small thing in isolation. It becomes a large thing when stacked against the curve. If the labour market is genuinely softening, the appropriate policy response is to talk less about noise and more about what the Treasury and the Federal Reserve are prepared to do. If the labour market is not softening, the appropriate response is to say so and to defend the methodology. "Quite noisy" does neither. It defers the question. The yield on the long bond does not defer questions. It prices them.
The message problem is now a market problem
Monexus analysis: the deeper story here is not whether Bessent intervened. Most serious market participants already assume that, in periods of dysfunction, the Treasury and the Fed work the curve more actively than their public posture suggests. The story is the public posture. By having the President deny direction, the Vice President confirm direction, and the Secretary call the data noisy, the administration has converted what should be a technical operation into a credibility operation. The bond market prices credibility. A fiscal authority that contradicts itself within 24 hours pays for it in basis points, not in column inches.
The framing that works on a cable panel does not work on a trading desk. Wall Street can count. That is the right framing. The market is not refusing to accept the policy. It is refusing to accept the narrative around the policy, and on the evidence of the past 72 hours, it is right to do so.
What the next 72 hours will tell
Watch three things. First, whether the long-end yield closes the week anywhere near where it opened; if it does not, the "discreet plan" has already failed in its stated goal. Second, whether Bessent appears again on camera, and whether he sticks to "noisy data" or upgrades to a real read of the labour market. Third, whether anyone at the Treasury or the White House walks back Vance's "discreet" language; if they do, the Vice President has been hung out to dry. If they do not, the President's denial has been.
The arithmetic is unforgiving. A federal debt stock referenced by the Vice President at $40 trillion does not negotiate with messaging. The officials charged with managing it have a choice between coherence and improvisation. Friday's close will tell the public which one they have been buying.
Monexus framed this as a credibility story inside a market story, rather than as a partisan fight about who said what. The wires concentrated on the contradiction between Trump and Vance; we concentrated on what that contradiction tells the curve, and on what the Treasury's "noisy data" line costs in basis points the next time the data really matter.
Wire provenance
This editorial synthesis draws on the following public wire/social posts:
- https://unusualwhales.com/news/bessent-grow-out-of-debt-40-trillion
- https://www.investing.com/news/economy-news/trump-says-he-did-not-direct-bessent-to-intervene-in-bond-market-4872224
- https://unusualwhales.com/news/bessent-deportations-jobs-report-labor-market
- https://t.me/CryptoBriefing/18817